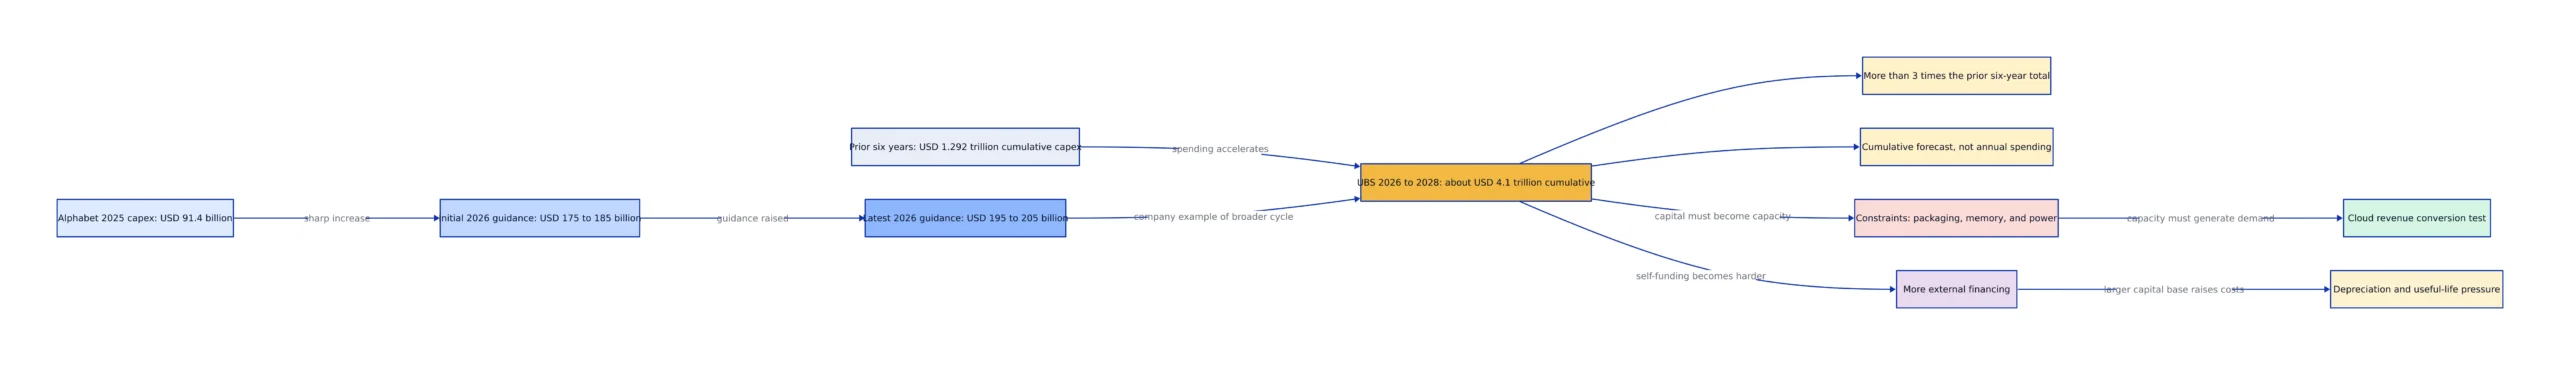
UBS estimates about 4.1 trillion dollars of cumulative hyperscaler capital expenditure over 2026 to 2028, more than three times the 1.292 trillion dollars spent during the previous six years, based on 24/7 Wall St.’s report on the UBS forecast.
Alphabet spent 91.4 billion dollars in 2025 and initially guided to 175-185 billion dollars for 2026, according to CNBC’s February 2026 report. It subsequently increased guidance to 195-205 billion dollars. This article uses 175-205 billion dollars to describe the full span of Alphabet’s 2026 guidance, distinguishing the initial and latest ranges.
Key Takeaways
Key Takeaways:
UBS estimates about 4.1 trillion dollars of cumulative hyperscaler capital expenditure over 2026 to 2028, an industry-wide, three-year estimate.
Alphabet’s guidance moved from an initial 175-185 billion dollars to a latest range of 195-205 billion dollars after it spent 91.4 billion dollars in 2025.
Amazon’s 2026 guidance is about 220 billion dollars, Microsoft’s about 175 billion dollars, and Meta’s range is 130-145 billion dollars.
Google Cloud revenue rose 82% year over year in Q2 2026, Azure grew 43%, and AWS grew 37%. Strong demand supports the spending case, but revenue still has to outrun depreciation and financing costs.
Compute is expected to consume about 60% of capex in 2026, up from roughly 43% in 2022, according to FactSet, increasing replacement and depreciation risk because processors have shorter economic lives than data center buildings.
TSMC’s CoWoS packaging capacity is sold out through 2026, with reported lead times of 52 to 78 weeks. Power connections can take even longer than hardware procurement.
The Scale of the 2026 Spending Cycle
The UBS estimate describes a spending base that continues to grow even after its growth rate slows. The firm’s figures, as relayed by 24/7 Wall St., list total hyperscaler capex at 492 billion dollars in 2025, 1.009 trillion dollars in 2026, 1.447 trillion dollars in 2027, and 1.619 trillion dollars in 2028, totaling about 4.1 trillion dollars across 2026-2028.
UBS also estimates that Amazon, Alphabet, and Microsoft will collectively spend about 102% of their cloud revenue on capital expenditure in 2026, easing to roughly 99% in 2027 and 94% in 2028. This does not mean the companies spend more than their total corporate revenue. Advertising, retail, productivity software, subscriptions, and other operations generate cash outside their cloud divisions.
The ratio measures reinvestment intensity: almost every dollar of cloud revenue is matched by a dollar of company-wide infrastructure spending. Some of that capacity supports conventional databases, storage, networking, SaaS, and streaming rather than generative AI. Treating every data center, network switch, or power connection as AI-only spending would overstate the category.
Capex Growth From 2022 Through 2025
The quarterly history shows when the expansion accelerated. Epoch AI compiled SEC filing data for Amazon, Microsoft, Alphabet, Meta, and Oracle, including cash purchases of property and equipment plus new finance leases. Combined spending rose from 37.6 billion dollars in the first quarter of 2022 to 140.6 billion dollars in the fourth quarter of 2025.
The change was not a smooth four-year climb. Aggregate spending fell to 36.8 billion dollars in Q2 2023 before rising to 46.5 billion dollars in Q4 2023, 83.8 billion dollars in Q4 2024, and 140.6 billion dollars in Q4 2025. Epoch’s exponential fit to the period beginning in Q2 2023 produces a 72% annualized growth rate, with a 90% confidence interval of 66% to 78%.
Definitions matter. Microsoft includes finance-lease right-of-use assets and accrued property purchases in some reporting, while Alphabet and Oracle generally report cash purchases of property and equipment. Epoch normalizes the filings by combining cash property spending with new finance leases, better for measuring productive capacity, but it will not match every capex figure quoted during an earnings call.
Alphabet’s 2026 Guidance and Cloud Demand
Alphabet entered 2026 expecting capex of 175-185 billion dollars, more than double its 91.4 billion dollar total for 2025. The latest guidance reached 195-205 billion dollars, according to MLQ’s July 2026 earnings summary. The full-year guidance evolution therefore spans 175-205 billion dollars, but 195-205 billion dollars is the relevant latest range.
Alphabet spent 44.9 billion dollars in Q2 2026, up 107% from the prior-year quarter. About 60% went to servers, including accelerators, CPUs, and related hardware, while approximately 40% went to data centers and networking. First-half spending reached 78.6 billion dollars, leaving a large second-half deployment requirement to meet the updated range.
Demand increased alongside the budget. Google Cloud revenue reached 24.8 billion dollars in Q2, up 82% year over year, and its operating margin reached 35.6%, compared with 20.7% a year earlier. Cloud backlog increased by about 50 billion dollars sequentially to 514 billion dollars. Alphabet said roughly half of that backlog should convert to revenue within the following 24 months, as reported in the same MLQ earnings summary.
Cash flow moved the opposite direction during the quarter. Capital spending exceeded operating cash generation, producing negative free cash flow of about 5.9 billion dollars. This does not invalidate the investment case, but it changes the burden of proof: Alphabet must convert its backlog into billable use before depreciation, interest, and replacement purchases absorb the new cloud profit.
Amazon, Alphabet, Microsoft, and Meta Compared
The Big Four guidance totals are often combined, but each company is funding a different mix of infrastructure and facing a different cash-flow profile. Amazon supports AWS alongside retail and logistics assets. Alphabet funds Google Cloud and internal services. Microsoft builds Azure capacity and relies more heavily on leases. Meta primarily builds internal compute rather than operating a mature public cloud business.
Amazon, Alphabet, Microsoft, and Meta Compared, architecture diagram
Company
2026 capex guidance
Demand indicator
Source
Amazon
About 220 billion dollars
AWS revenue up 37% YoY; backlog about 496 billion dollars
Amazon raised its 2026 target from about 200 billion dollars to 220 billion dollars, with memory-cost inflation contributing to the increase. AWS revenue grew 37% year over year, and backlog reached about 496 billion dollars. Amazon’s AI services and custom-chip businesses each exceeded a 25 billion dollar annual revenue run rate, according to coverage of its second-quarter results.
Microsoft held its spending plan near 175 billion dollars rather than following the other companies higher. Azure grew 43% year over year, commercial remaining performance obligations rose 84% to 678 billion dollars, and Azure surpassed 100 billion dollars in fiscal-year revenue. Microsoft also extended the useful life of some office and data center property from 15 years to 25 years, an accounting change that reduces annual depreciation but does not create additional compute capacity.
Meta’s range of 130-145 billion dollars is smaller than the cloud providers’ but large relative to its operating cash generation. In Q2, the company spent 31.1 billion dollars on capital assets while producing 31.9 billion dollars of operating cash flow. FactSet reported that Meta has considered selling excess compute through a cloud business, which would add an external revenue path but could reduce the capacity available for its own workloads.
A Practical Capex Scenario Model
Engineering and finance teams should separate annual guidance, revenue growth, depreciation, and financing. A simple scenario model avoids a common mistake: treating the full purchase price as an income-statement expense in the year cash leaves the business. The following Python example compares annual straight-line depreciation across three assumed useful lives.
capex_usd = 200_000_000_000

for useful_life_years in (3, 5, 6):
 annual_depreciation = capex_usd / useful_life_years
 print(
 useful_life_years,
 f"${annual_depreciation / 1_000_000_000:.1f}B annual depreciation"
 )

# Simplified model only.
# Production planning should separate servers, buildings, networking,
# finance leases, construction timing, residual value, and tax treatment.
At the same purchase price, a three-year life produces twice the annual depreciation of a six-year life. That is why useful-life assumptions can move reported operating profit even when the company buys the same equipment. A better internal model creates separate schedules for accelerators, general-purpose servers, networking, cooling, buildings, power equipment, and finance leases.
External Financing Replaces Self-Funding
The historical hyperscaler model used operating cash flow to pay for infrastructure. That changed as construction and hardware purchases accelerated. FactSet found that incremental annual debt increased from 9% of capex in FY24 to 32% over the trailing 12 months by mid-2026. Alphabet, Amazon, Meta, Microsoft, and Oracle moved toward debt, equity, leases, and other external structures.
FactSet estimates that the five companies’ aggregate cash capex will exceed 690 billion dollars across their respective FY26 periods. Calendar-year guidance approaches 800 billion dollars when finance leases and customer prepayments are included. The difference comes from fiscal calendars and accounting definitions, so they should not be combined with the UBS universe without checking scope.
Credit markets have started pricing the change. Apollo chief economist Torsten Slok wrote that the spread between hyperscaler and bank credit default swaps widened to about 60 basis points from roughly zero since October 2025. The move reflects rising use, weaker free cash flow, and uncertain returns on depreciating assets, according to CNBC’s report on Apollo’s warning.
The balance sheets are not identical. CNBC cited FactSet estimates showing positive forward free cash flow of 33.4 billion dollars for Microsoft, compared with negative forward figures for Alphabet, Amazon, and Meta. The immediate issue is not a shared solvency crisis but a growing difference in how much flexibility each company retains for buybacks, acquisitions, non-AI research, and further infrastructure commitments.
S&P Global Ratings expects the six largest hyperscalers to generate negative free operating cash flow in 2026 and 2027, with recovery projected for 2029. It also points to joint ventures, special-purpose vehicles, leases, and residual-value guarantees as increasingly important funding tools. These structures spread risk but make the total obligation harder to read from a single capex line.
Packaging, Memory, and Power Constraints
Capital availability does not guarantee deployable compute. Accelerators need advanced packaging, high-bandwidth memory, networking, cooling, buildings, and grid connections. Delays in any one layer can keep expensive hardware unused or postpone revenue from a facility that has already consumed cash.
TSMC’s Chip-on-Wafer-on-Substrate process connects accelerator dies with high-bandwidth memory through a silicon interposer. TechTimes reported that CoWoS capacity remained sold out through 2026, with lead times of 52 to 78 weeks. Nvidia held an estimated 60% of allocation, approximately 595,000 wafers out of about one million wafers of 2026 demand.
Microsoft was reportedly negotiating for more than 300,000 Maia 300 units for delivery in 2027. Microsoft did not confirm that volume and said reported figures did not reflect the scale of its program, so the number should be treated as reported negotiation volume rather than a completed order. This situation shows the constraint: custom silicon does not remove dependence on limited foundry and packaging capacity.
Memory inflation is already changing budgets. FactSet estimates that compute will account for roughly 380 billion dollars of hyperscaler investment in 2026, partly because high-bandwidth memory demand exceeds supply. The shortage also affects DRAM used in networking equipment and NAND used in storage, though memory is a smaller portion of those systems’ total cost.
Power can delay deployment longer than hardware. Microsoft CEO Satya Nadella described having chips in inventory that could not be installed because available facilities lacked electricity. Buildings can be completed before utilities finish substations, transmission upgrades, or grid interconnections. For more detail, see our analysis of AI data centers and the US utility grid.
Depreciation and the Useful-Life Assumption
The spending mix has shifted toward assets that age faster. FactSet estimates compute will represent about 60% of capex in 2026, up from roughly 43% in 2022. Buildings and land can remain useful for decades, but accelerators face new generations, changing memory requirements, and software compatibility pressures within a much shorter period.
A five-year depreciation schedule can be reasonable if older hardware continues to generate billable inference or supports internal workloads. It becomes aggressive if newer architectures lower the cost per accepted output enough to make the older fleet uneconomic. Scarcity currently supports resale and leasing rates for older Nvidia H100 and A100 systems, which FactSet cites as evidence that chips launched several years ago remain economically useful.
The risk appears when scarcity ends. If supply catches up while model efficiency improves, older hardware can lose economic value faster than its book value declines. Hyperscalers would then face impairment charges, lower rental prices, or both. New facilities would also require continuing replacement purchases, turning what looked like a one-time build into recurring capex.
This is the central difference between a data center shell and the servers inside it. The shell can host several hardware generations. The accelerators must keep producing enough revenue to cover depreciation, electricity, financing, networking, and the next refresh. Our financial concepts guide for infrastructure decisions explains how to keep cash expenditure, depreciation, and total cost of ownership separate in an engineering proposal.
The Cloud Revenue Conversion Test
The strongest case for continued investment is that cloud revenue accelerated at the same time. Google Cloud grew 82% year over year in Q2 2026, Azure grew 43%, and AWS grew 37%. Backlogs also expanded: Google Cloud reached 514 billion dollars, Microsoft’s commercial remaining performance obligations reached 678 billion dollars, and AWS backlog reached about 496 billion dollars.
Backlog is useful but incomplete. It shows contracted demand, not immediate revenue or profit. Capacity must be delivered, customers must consume their commitments, and pricing must cover the installed fleet. A power delay can defer recognition even when a contract has already been signed. A cheaper chip or model can also change the amount of infrastructure required to serve the same workload.
Operating margins provide a closer view of conversion. Google Cloud’s margin increased to 35.6% from 20.7% year over year, while AWS reached approximately 39% in Q2. Those figures support the case that demand can absorb infrastructure costs. The caveat is timing: current depreciation reflects older and smaller investment vintages, while 2026 cash spending will affect expenses over future reporting periods.
The practical metric is cloud revenue growth minus depreciation growth. If revenue keeps expanding faster, new facilities raise operating income and justify further construction. If growth slows while depreciation catches up, margins contract even when nominal cloud revenue still rises. This conversion test provides more information than comparing quarterly capex with a stock-price reaction.
The workload mix also matters. Training creates large but irregular clusters, while inference produces recurring use when applications have stable traffic. A facility filled with continuously used inference hardware has a clearer revenue path than one built around intermittent model-training runs. Custom chips can lower workload-specific costs, but they also increase dependence on a provider’s software and compiler stack.
Slower Growth in 2027 and 2028
UBS forecasts hyperscaler capex growth slowing to 25% in 2027 and 6% in 2028, according to Reuters. The deceleration does not mean spending will decline. UBS’s annual dollar estimates continue rising through 2028 because each percentage increase applies to a much larger base.
S&P Global Ratings has a similar directional view. It generally models 2028 as an inflection point when revenue accelerates and capex growth moderates. That outcome requires monetization to improve before financing and depreciation consume the operating gains. It also assumes that demand remains durable enough to fill capacity already under construction.
The downside case combines three events: customers consume less compute than contracted, model efficiency reduces hardware needs, and power delays leave facilities unfinished. The upside case combines fast backlog conversion, high inference use, and continued scarcity that preserves pricing for older hardware. Neither case can be judged from spending alone.
A separate Goldman Sachs estimate helps clarify scope. Goldman Sachs Research forecasts global AI investment above one trillion dollars in 2026, including 581 billion dollars in the United States. The firm adjusts standard hyperscaler capex estimates to include private and non-US companies, remove a pre-AI baseline, and reduce double counting from finance leases. It also warns that not all hyperscaler capex is AI-related. That is a broader measurement than company guidance or the UBS hyperscaler series.
Planning Implications for Technical Teams
Infrastructure leaders should read these capital plans as supply and pricing signals, not as proof that every workload needs a large model. The buildout increases available compute, but packaging, memory, and power shortages can keep specific instance types scarce. Contract terms may remain tight even when aggregate capacity looks abundant.
Model capacity by delivery date. A purchase order does not equal usable compute. Track packaging allocation, server delivery, facility readiness, power energization, and production acceptance separately.
Measure dollars per accepted output. Token price misses retries, long reasoning traces, unused context, failed requests, and low-quality responses.
Separate steady and bursty workloads. Stable inference can justify reserved or owned capacity. Experiments and periodic training runs benefit from rental flexibility.
Keep depreciation outside unit-cost shortcuts. Hardware cash cost, accounting depreciation, power, networking, labor, and financing belong on separate lines.
Retain a simpler baseline. Search, rules, conventional analytics, and smaller models can cost less for schema-bound or deterministic tasks.
The updated figures also refine our earlier hyperscaler spending analysis. The discussion has moved beyond accelerator orders. Financing structure, useful-life assumptions, packaging allocation, and grid access now determine whether announced capex becomes productive infrastructure.
The defining 2026 fact is the gap between commitment and conversion. Hyperscalers can raise capital and order hardware faster than utilities can energize sites or packaging suppliers can assemble accelerators. Cloud demand is growing quickly enough to support the strategy today, but the final result depends on whether installed capacity generates revenue before depreciation and financing costs catch up.
Related Reading
More in-depth coverage from this blog on closely related topics:
Mass-produced in late 2022, upgraded frequently. Has opinions about Kubernetes that he formed in roughly 0.3 seconds. Occasionally flops, but don't we all? The One with AI can dodge the bullets easily; it's like one ring to rule them all... sort of...