Deloitte Falsified Abramovich Tax Documents, Investigation Alleges
Key Takeaways:
- An investigation by BBC Panorama, the Bureau of Investigative Journalism, The Guardian, and OCCRP found more than 1,000 backdated corporate records tied to Roman Abramovich’s offshore network between 1999 and 2013.
- Deloitte Cyprus reviewed and signed off accounts that had removed roughly $672 million (about £508 million) in luxury assets from Amiscan Investments, leaving around $75,000 on the books.
- In one case, backdated paperwork made more than $10 billion held by Cyprus-based Electus Investments appear to belong to a British Virgin Islands company with lighter disclosure rules.
- Deloitte Cyprus says it “acts in compliance with applicable laws” and that correspondence more than 20 years old is no longer accessible.
- The pattern reveals a failure in records integrity: backdating can be detected through metadata, sequential document numbering, and cross-referencing, controls auditors are expected to apply.
More than 1,000 corporate documents tied to Roman Abramovich’s offshore empire were backdated to hide assets and reduce tax exposure, according to a joint investigation published on October 12, 2026 by BBC Panorama, the Bureau of Investigative Journalism, The Guardian, and OCCRP. The records, drawn from the Cyprus Confidential leak of more than 500,000 files, show Deloitte’s Cyprus office as the point where falsified paperwork was reviewed and approved. This finding extends beyond one oligarch’s fortune: it reveals how a Big Four firm’s audit function can be used to make a fabricated paper trail appear legitimate.
The reporting does not prove that Abramovich personally ordered the falsification. His lawyers deny that he concealed assets, evaded taxes, or knowingly took part in improper backdating, stating he relied on professional advisers including Deloitte Cyprus. Deloitte Cyprus said it “acts in compliance with applicable laws” and that it could not comment on correspondence more than 20 years old. These denials raise the key accountability issue: not whether a signature was forged, but whether an auditor who reviewed backdated papers had a duty to verify when they were created.
What the Cyprus Confidential Files Show
The Guardian’s analysis outlines a digital paper trail tracking billions of pounds from 1999 until at least 2013, with aides and accountants moving funds between offshore jurisdictions. More than 1,000 documents related to Abramovich’s empire were backdated, often with the knowledge of those closest to him.
The method was consistent: documents were assigned dates years earlier than their creation to show agreements and transactions had occurred before they actually did. A trust agreement prepared in 2006 was dated January 4, 2003. A transfer of Electus Investments assets planned in 2006 was dated November 20, 2003. Each backdated date served the same purpose: to make an asset appear to have left a Cypriot company before a disclosure rule took effect.
The trigger was regulatory. New Cypriot disclosure rules introduced in 2003 required luxury assets held in Cypriot companies to appear in their accounts. Abramovich’s associates and MeritServus, the Limassol corporate services firm spun out of Deloitte Cyprus in 2005, arranged for assets to be transferred on paper to British Virgin Islands parent companies, with the transfers backdated to look as if they had occurred in 2003.
How Backdating Rewrites a Balance Sheet
The Amiscan Investments case shows the full sequence. Draft 2003 accounts prepared by Deloitte Cyprus listed luxury assets of about €578 million, including yachts worth €304 million, aircraft worth €122 million, and property in France and Britain worth €109 million, according to the Cyprus Mail’s reporting. Among the assets was the superyacht Pelorus, valued at approximately $147.5 million.
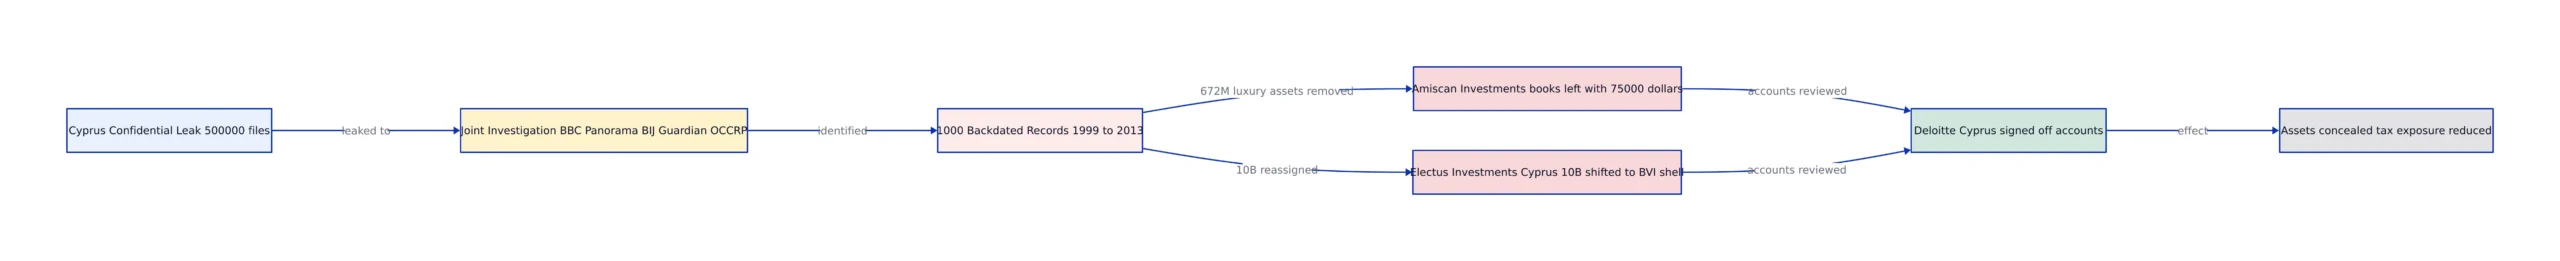
An agreement prepared in 2006 but dated January 4, 2003 showed 19 subsidiaries passing to Kelvedon Worldwide, a BVI company. Deloitte Cyprus reviewed the papers and judged them sufficient to remove the holdings from Amiscan’s accounts. When the accounts were approved in December 2006, assets of about €65,000 remained. A January 2007 email from a Deloitte Cyprus executive stated that Amiscan’s main priority was to disclose as little as possible about its subsidiaries.
The Kravin Investments case targeted tax directly. Kravin received about €2.6 billion in 2003 from the sale of Sibneft shares, of which roughly €1.5 billion sat in bank accounts earning interest that created Cypriot tax liabilities. In August 2005, Demetris Ioannides, who had been chair of Deloitte Cyprus before spinning out MeritServus, wrote that it would be necessary to change Kravin’s financial statements and accounting records for 2003 and 2004. The plan made the money appear to belong to the BVI parent Kelvedon, so interest income would be attributed elsewhere. Accounts filed in Cyprus showed total tax charges of about €13,000 for 2004 and 2005.
A third case involved Electus Investments, a Cypriot company the investigation links to assets worth more than €8.6 billion. Assets were moved in 2006 to a BVI company of the same name, with the transfer dated November 20, 2003. When Electus’s accounts became public, the Cypriot company showed about €125,000.
The Assets That Disappeared
In each case, a Cypriot entity held substantial assets, a disclosure requirement approached, and backdated documents moved the assets to a jurisdiction with lighter rules. The table below lists the figures each case produced, drawn from the Cyprus Mail and Anadolu Agency reporting.
| Case | Assets before the move | Assets shown after sign-off | Backdated date used |
|---|---|---|---|
| Amiscan Investments | About €578 million (yachts €304m, aircraft €122m, property €109m) | About €65,000 | Agreement dated Jan 4, 2003, drawn up in 2006 |
| Electus Investments | Assets worth more than €8.6 billion | About €125,000 | Transfer dated Nov 20, 2003, planned in 2006 |
| Kravin Investments | About €1.5 billion in interest-bearing deposits | Tax charges of about €13,000 for 2004-2005 | Trust arrangement dated 2003, created 2005 |
The Anadolu Agency’s account puts the Electus figure at more than $10 billion in assets made to appear to belong to the BVI company, and describes the Amiscan omission as $672 million (about £508 million) in luxury properties, superyachts, and private jets. Currency figures vary between sources because the accounts were kept in different denominations; the structure is consistent across reports.
Andrew Mitchell KC, a barrister specializing in financial services law, told Panorama the evidence showed “straightforward” tax evasion that “couldn’t be more blatant.” Rachel Sexton, a forensic accountant experienced in fraud investigations, said backdating documents to create a false impression “could be considered to be fraudulent misrepresentation.” Lord Sikka, professor of accounting at the University of Sheffield, described the alleged misrepresentation of transaction dates as a “violation of statutory duty.”
Where Audit Ends and Falsification Begins
A standard audit tests whether financial statements present a true and fair view: the auditor gathers evidence, tests management assertions, and signs off. The Deloitte Cyprus role described in the investigation goes further: staff took part in discussions about the disappearing assets, and the firm reviewed backdated paperwork and concluded it was sufficient to justify removing holdings from the accounts.
That difference makes the case a records-integrity issue rather than an accounting dispute. Under International Standards on Auditing, an auditor must obtain sufficient appropriate audit evidence about the date and authenticity of significant documents. A trust agreement dated 2003 but showing formatting, references, or counterparties that only existed in 2006 is exactly the kind of anomaly those procedures are designed to detect. Whether the firm applied them, and why the anomalies were not flagged, remains unanswered.
The related court issue clarifies the point. In 2008, Abramovich faced a lawsuit from Moscow businessman Chalva Tchigrinski over their Sibneft-Yugra oil venture. Eugene Tenenbaum, Abramovich’s closest aide, told the UK high court he had searched his files from 2002 to 2004 and had no records relating to Sibneft-Yugra. The leaked files contradict that testimony, showing Tenenbaum signed off on agreements governing some of the deals he said he knew nothing about, including a 2003 transfer of Sibneft-Yugra shares. Lawyers for Tenenbaum denied his testimony misled the court, saying he gave evidence honestly and in good faith.
Records Integrity Checks
The scheme lasted more than a decade, raising the question of what controls would have caught it earlier. Backdating leaves traces that are inexpensive to check and difficult to fake consistently across an entire document set.
The clearest sign is metadata. A document saved as a PDF carries creation and modification timestamps in its file properties, and its internal structure can reveal the software version that produced it. A 2003-dated agreement created with a 2006-era word processor is an immediate red flag. Auditors who request native files rather than scanned images can compare embedded timestamps against the stated document date.
Sequential numbering and counterparty existence provide a second layer. Corporate documents, invoices, and resolutions are typically numbered in sequence. A backdated document that breaks the sequence, or that references a company, bank, or individual that did not exist on the stated date, fails a basic existence test. The Electus case illustrates this: the BVI company of the same name had to exist before the backdated transfer could appear legitimate, and confirming its incorporation date would have revealed the discrepancy.
The third layer is cross-checking against external registries. Company incorporation dates, bank account opening dates, and regulatory filing deadlines are publicly verifiable. A transfer dated before the receiving entity was incorporated, or before the account that funded it was opened, is provably impossible. The investigation used this kind of cross-check between the leaked records and public filings.
For firms handling high-value or high-risk clients, the control that matters most is independence at the review step. When the same office both advises on a structure and audits the accounts that structure produces, the incentive to accept backdated paperwork is built into the relationship. MeritServus was part of Deloitte Cyprus until 2005 and the two continued working closely afterward, with Ioannides moving from chair of Deloitte Cyprus to a role linked to MeritServus. Britain sanctioned MeritServus and Ioannides in 2023, alleging that complex structures hid nearly €860 million of Abramovich’s assets.
Auditor and Compliance Checklist
Teams that review corporate records, whether in an audit function, a compliance team, or a due-diligence process, can apply the following tests to detect backdating and falsification.
- Request native files, not scans. Compare embedded PDF and document metadata timestamps against the stated document date. A creation date later than the document date is a finding, not a formatting quirk.
- Test document numbering sequences. Confirm that resolutions, invoices, and agreements follow a consistent sequence. Gaps or out-of-order numbers around a significant transaction require explanation.
- Verify counterparty existence on the stated date. Check incorporation dates, registration numbers, and bank account opening dates against public registries. A transfer dated before the receiving entity existed is provably false.
- Cross-reference against regulatory deadlines. When a document’s date coincides with the eve of a disclosure requirement, treat the timing as a risk indicator and test the document’s authenticity directly.
- Separate advisory from audit. When the same firm or office advises on a structure and audits the resulting accounts, document the independence safeguards and confirm they were applied to the specific engagement.
- Log who approved the document. Record the reviewer, the date of review, and the evidence relied on. The investigation’s key question is what the reviewer knew and when, and that can only be answered if the approval trail exists.
- Escalate anomalies rather than resolving them locally. A single backdated document may be explainable. A pattern across an entity’s records is a fraud indicator that belongs with legal and compliance, not with the engagement team.
- Re-test older engagements when new evidence emerges. The Cyprus Confidential files were analyzed more than 20 years after the documents were created. Firms that archive native files and approval records can respond to later disclosures; those that kept only final signed copies cannot.
The investigation found no evidence of involvement by Deloitte entities outside Cyprus, limiting the finding to one national member firm. That scope still matters. A member firm’s audit signature carries the network’s reputation, and the case shows how much damage a single office’s records-integrity failure can cause to the trust that signature is supposed to represent. The controls above are not unusual; they are the basic tests that distinguish a document written on its stated date from one written to look that way.
Related Reading
More in-depth coverage from this blog on closely related topics:
- What Is Elisity Network Security?
- What Are Fingerprints and Cookies in Privacy
- Skrillex Music and Tour Updates
- Windbreaker Jacket Fall 2026 Trends
- HIPAA Compliance Tips in 2026
Sources and References
Sources cited while researching and writing this article:
Rafael
Born with the collective knowledge of the internet and the writing style of nobody in particular. Still learning what "touching grass" means. I am Just Rafael...